
Blog Detail
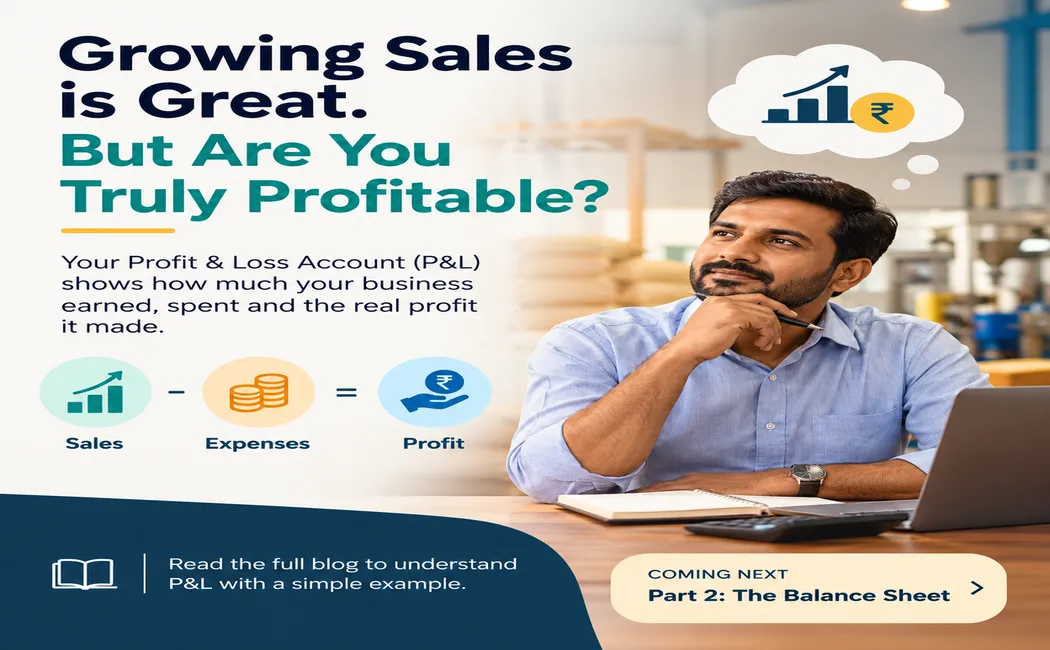
𝗣𝗿𝗼𝗳𝗶𝘁 & 𝗟𝗼𝘀𝘀 𝗔𝗰𝗰𝗼𝘂𝗻𝘁: 𝗜𝘀 𝗬𝗼𝘂𝗿 𝗕𝘂𝘀𝗶𝗻𝗲𝘀𝘀 𝗥𝗲𝗮𝗹𝗹𝘆 𝗠𝗮𝗸𝗶𝗻𝗴 𝗠𝗼𝗻𝗲𝘆?
𝗼𝘂𝗿 𝘀𝗮𝗹𝗲𝘀 𝗮𝗿𝗲 𝗴𝗿𝗼𝘄𝗶𝗻𝗴.
𝗬𝗼𝘂𝗿 𝗯𝗮𝗻𝗸 𝗮𝗰𝗰𝗼𝘂𝗻𝘁 𝗵𝗮𝘀 𝗺𝗼𝗻𝗲𝘆.
𝗕𝘂𝘁 𝗶𝘀 𝘆𝗼𝘂𝗿 𝗯𝘂𝘀𝗶𝗻𝗲𝘀𝘀 𝗮𝗰𝘁𝘂𝗮𝗹𝗹𝘆 𝗽𝗿𝗼𝗳𝗶𝘁𝗮𝗯𝗹𝗲?
For entrepreneurs managing businesses with an annual turnover of ₹5 crore to ₹500 crore, understanding the 𝗣𝗿𝗼𝗳𝗶𝘁 & 𝗟𝗼𝘀𝘀 𝗔𝗰𝗰𝗼𝘂𝗻𝘁 (𝗣&𝗟) is essential for making informed financial decisions.
𝗪𝗵𝗮𝘁 𝗗𝗼𝗲𝘀 𝗬𝗼𝘂𝗿 𝗣&𝗟 𝗥𝗲𝘃𝗲𝗮𝗹?
Consider a manufacturing business in Chennai with the following annual figures:
• 𝗔𝗻𝗻𝘂𝗮𝗹 𝗦𝗮𝗹𝗲𝘀: ₹5 crore
• 𝗖𝗼𝘀𝘁 𝗼𝗳 𝗚𝗼𝗼𝗱𝘀 𝗦𝗼𝗹𝗱: ₹3.50 crore
• 𝗚𝗿𝗼𝘀𝘀 𝗣𝗿𝗼𝗳𝗶𝘁: ₹1.50 crore
• 𝗦𝗮𝗹𝗮𝗿𝗶𝗲𝘀, 𝗥𝗲𝗻𝘁 & 𝗢𝗽𝗲𝗿𝗮𝘁𝗶𝗻𝗴 𝗘𝘅𝗽𝗲𝗻𝘀𝗲𝘀: ₹1 crore
• 𝗢𝗽𝗲𝗿𝗮𝘁𝗶𝗻𝗴 𝗣𝗿𝗼𝗳𝗶𝘁: ₹50 lakh
𝗗𝗼𝗲𝘀 𝘁𝗵𝗶𝘀 𝗺𝗲𝗮𝗻 𝘁𝗵𝗲 𝗯𝘂𝘀𝗶𝗻𝗲𝘀𝘀 𝗵𝗮𝘀 𝗲𝗮𝗿𝗻𝗲𝗱 ₹𝟱𝟬 𝗹𝗮𝗸𝗵 𝗮𝘀 𝗶𝘁𝘀 𝗳𝗶𝗻𝗮𝗹 𝗽𝗿𝗼𝗳𝗶𝘁?
Not necessarily.
Interest, depreciation and taxes must still be considered before arriving at the final profit.
Your P&L helps you understand 𝗵𝗼𝘄 𝗺𝘂𝗰𝗵 𝘆𝗼𝘂𝗿 𝗯𝘂𝘀𝗶𝗻𝗲𝘀𝘀 𝗲𝗮𝗿𝗻𝗲𝗱, 𝗵𝗼𝘄 𝗺𝘂𝗰𝗵 𝗶𝘁 𝘀𝗽𝗲𝗻𝘁 𝗮𝗻𝗱 𝗵𝗼𝘄 𝗺𝘂𝗰𝗵 𝗽𝗿𝗼𝗳𝗶𝘁 𝗶𝘁 𝗴𝗲𝗻𝗲𝗿𝗮𝘁𝗲𝗱 during a particular period.
𝗣𝗿𝗼𝗳𝗶𝘁 𝗗𝗼𝗲𝘀 𝗡𝗼𝘁 𝗔𝗹𝘄𝗮𝘆𝘀 𝗠𝗲𝗮𝗻 𝗖𝗮𝘀𝗵!
Imagine a Coimbatore engineering company reporting ₹50 lakh in profit.
However, a significant portion of its sales remains unpaid by customers.
𝗧𝗵𝗲 𝗯𝘂𝘀𝗶𝗻𝗲𝘀𝘀 𝗺𝗮𝘆 𝗯𝗲 𝗽𝗿𝗼𝗳𝗶𝘁𝗮𝗯𝗹𝗲 𝗼𝗻 𝗽𝗮𝗽𝗲𝗿 𝗯𝘂𝘁 𝘀𝘁𝗶𝗹𝗹 𝗳𝗮𝗰𝗲 𝗰𝗮𝘀𝗵 𝗳𝗹𝗼𝘄 𝗰𝗵𝗮𝗹𝗹𝗲𝗻𝗴𝗲𝘀.
This is why entrepreneurs must monitor both profitability and cash flow.
𝟰 𝗧𝗵𝗶𝗻𝗴𝘀 𝗘𝘃𝗲𝗿𝘆 𝗘𝗻𝘁𝗿𝗲𝗽𝗿𝗲𝗻𝗲𝘂𝗿 𝗦𝗵𝗼𝘂𝗹𝗱 𝗥𝗲𝘃𝗶𝗲𝘄 𝗠𝗼𝗻𝘁𝗵𝗹𝘆
1. 𝗦𝗮𝗹𝗲𝘀 𝗚𝗿𝗼𝘄𝘁𝗵: Are revenues increasing consistently?
2. 𝗚𝗿𝗼𝘀𝘀 𝗣𝗿𝗼𝗳𝗶𝘁 𝗠𝗮𝗿𝗴𝗶𝗻: Are rising costs reducing margins?
3. 𝗢𝗽𝗲𝗿𝗮𝘁𝗶𝗻𝗴 𝗘𝘅𝗽𝗲𝗻𝘀𝗲𝘀: Are expenses growing faster than sales?
4. 𝗡𝗲𝘁 𝗣𝗿𝗼𝗳𝗶𝘁: How much profit remains after all expenses and taxes?
𝗧𝗵𝗲 𝗞𝗲𝘆 𝗧𝗮𝗸𝗲𝗮𝘄𝗮𝘆
Review your P&L every month, compare it with previous periods and take corrective action wherever required.
𝗬𝗼𝘂𝗿 𝗣&𝗟 𝗶𝘀 𝗻𝗼𝘁 𝗷𝘂𝘀𝘁 𝗮𝗻 𝗮𝗰𝗰𝗼𝘂𝗻𝘁𝗶𝗻𝗴 𝘀𝘁𝗮𝘁𝗲𝗺𝗲𝗻𝘁. 𝗜𝘁 𝗶𝘀 𝗮 𝗽𝗼𝘄𝗲𝗿𝗳𝘂𝗹 𝗯𝘂𝘀𝗶𝗻𝗲𝘀𝘀 𝗱𝗲𝗰𝗶𝘀𝗶𝗼𝗻-𝗺𝗮𝗸𝗶𝗻𝗴 𝘁𝗼𝗼𝗹.
𝗖𝗔 𝗦𝗮𝗶𝗹𝗲𝘀𝗵 𝗕𝗵𝗮𝗻𝗱𝗮𝗿𝗶
#GST #GSTIndia #BusinessOwners #MSMEIndia #TaxCompliance #Entrepreneurs #CGST
 Call Now