
Blog Detail
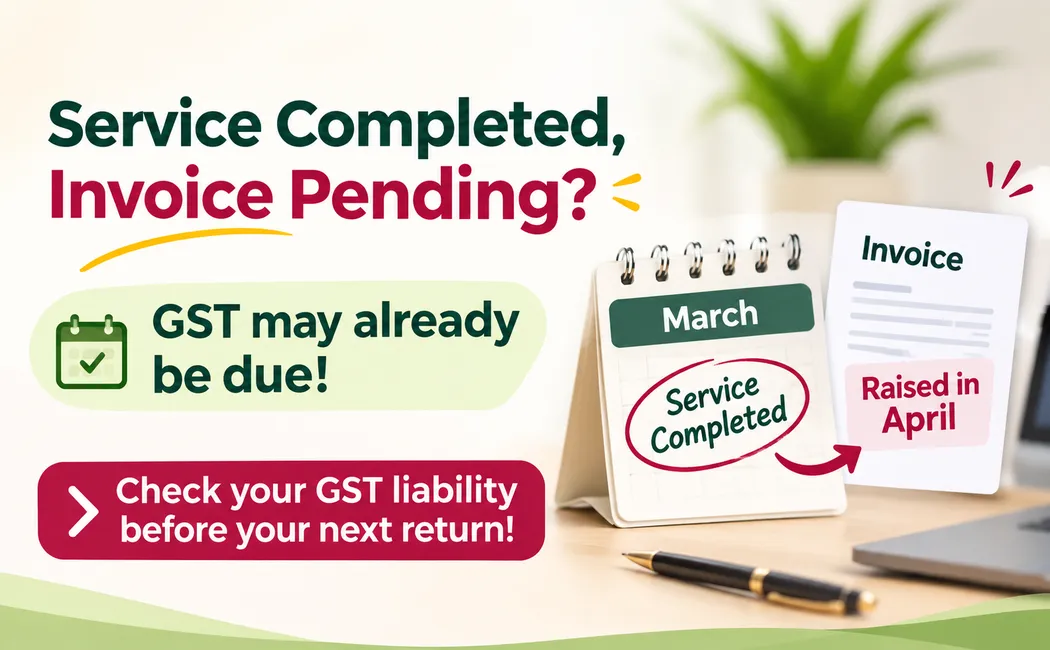
𝗚𝗦𝗧 𝗧𝗶𝗺𝗲 𝗼𝗳 𝗦𝘂𝗽𝗽𝗹𝘆 𝗼𝗳 𝗦𝗲𝗿𝘃𝗶𝗰𝗲𝘀: 𝗜𝗻𝘃𝗼𝗶𝗰𝗲 𝗥𝗮𝗶𝘀𝗲𝗱 𝗟𝗮𝘁𝗲𝗿 – 𝗪𝗵𝗲𝗻 𝗜𝘀 𝗚𝗦𝗧 𝗣𝗮𝘆𝗮𝗯𝗹𝗲?
Jethalal, owner of 𝗚𝗮𝗱𝗮 𝗘𝗹𝗲𝗰𝘁𝗿𝗼𝗻𝗶𝗰𝘀 𝗦𝗲𝗿𝘃𝗶𝗰𝗲𝘀, 𝗖𝗵𝗲𝗻𝗻𝗮𝗶, provides annual maintenance services to Taarak Mehta's company, which has a turnover of ₹50 crore.
The contract value is ₹12 lakh plus 18% GST.
𝗦𝗲𝗿𝘃𝗶𝗰𝗲 𝗰𝗼𝗺𝗽𝗹𝗲𝘁𝗲𝗱: 20th March 2026
𝗜𝗻𝘃𝗼𝗶𝗰𝗲 𝗿𝗮𝗶𝘀𝗲𝗱: 25th April 2026
𝗣𝗮𝘆𝗺𝗲𝗻𝘁 𝗿𝗲𝗰𝗲𝗶𝘃𝗲𝗱: 10th May 2026
𝗖𝗮𝗻 𝗝𝗲𝘁𝗵𝗮𝗹𝗮𝗹 𝗽𝗮𝘆 𝗚𝗦𝗧 𝗶𝗻 𝗔𝗽𝗿𝗶𝗹 𝗯𝗲𝗰𝗮𝘂𝘀𝗲 𝘁𝗵𝗲 𝗶𝗻𝘃𝗼𝗶𝗰𝗲 𝘄𝗮𝘀 𝗿𝗮𝗶𝘀𝗲𝗱 𝗶𝗻 𝗔𝗽𝗿𝗶𝗹?
𝗡𝗼, 𝗴𝗲𝗻𝗲𝗿𝗮𝗹𝗹𝘆.
Under 𝗦𝗲𝗰𝘁𝗶𝗼𝗻 𝟯𝟭(𝟮) 𝗼𝗳 𝘁𝗵𝗲 𝗖𝗚𝗦𝗧 𝗔𝗰𝘁, a service invoice must ordinarily be issued within 30 days of providing the service.
Here, the invoice was issued after the prescribed period.
Under 𝗦𝗲𝗰𝘁𝗶𝗼𝗻 𝟭𝟯(𝟮), the time of supply would therefore be 𝟮𝟬𝘁𝗵 𝗠𝗮𝗿𝗰𝗵 𝟮𝟬𝟮𝟲, assuming no earlier payment.
GST of ₹𝟮.𝟭𝟲 𝗹𝗮𝗸𝗵 would be attributable to March, not April.
𝗪𝗵𝗮𝘁 𝗶𝗳 𝗧𝗮𝗮𝗿𝗮𝗸 𝗠𝗲𝗵𝘁𝗮 𝗽𝗮𝗶𝗱 ₹𝟱 𝗹𝗮𝗸𝗵 𝗶𝗻 𝗮𝗱𝘃𝗮𝗻𝗰𝗲 𝗼𝗻 𝟭𝟬𝘁𝗵 𝗠𝗮𝗿𝗰𝗵?
For taxable services, GST liability generally arises upon receipt of the advance, to the extent received.
Therefore, 𝗚𝗦𝗧 𝗼𝗻 𝘁𝗵𝗲 𝗮𝗱𝘃𝗮𝗻𝗰𝗲 𝗮𝗿𝗶𝘀𝗲𝘀 𝗶𝗻 𝗠𝗮𝗿𝗰𝗵, even before the service is completed.
𝗪𝗵𝗮𝘁 𝗶𝗳 𝗝𝗲𝘁𝗵𝗮𝗹𝗮𝗹 𝗽𝗿𝗼𝘃𝗶𝗱𝗲𝘀 𝗰𝗼𝗻𝘁𝗶𝗻𝘂𝗼𝘂𝘀 𝗺𝗮𝗶𝗻𝘁𝗲𝗻𝗮𝗻𝗰𝗲 𝘀𝗲𝗿𝘃𝗶𝗰𝗲𝘀?
For qualifying continuous services, invoice timing depends on contractual payment due dates, receipt of payment or completion of specified milestones under 𝗦𝗲𝗰𝘁𝗶𝗼𝗻 𝟯𝟭(𝟱).
𝗪𝗵𝗮𝘁 𝗦𝗵𝗼𝘂𝗹𝗱 𝗕𝘂𝘀𝗶𝗻𝗲𝘀𝘀 𝗢𝘄𝗻𝗲𝗿𝘀 𝗥𝗲𝘃𝗶𝗲𝘄?
Track service completion dates and invoice deadlines.
Reconcile advances with GST liability.
Review annual maintenance and milestone-based contracts.
Verify the correct GST reporting period.
𝗞𝗲𝘆 𝗧𝗮𝗸𝗲𝗮𝘄𝗮𝘆: GST liability depends on statutory time-of-supply rules, not simply when your accountant raises an invoice.
𝗜𝘀 𝘆𝗼𝘂𝗿 𝗯𝘂𝘀𝗶𝗻𝗲𝘀𝘀 𝗿𝗲𝗽𝗼𝗿𝘁𝗶𝗻𝗴 𝘀𝗲𝗿𝘃𝗶𝗰𝗲 𝗶𝗻𝗰𝗼𝗺𝗲 𝗶𝗻 𝘁𝗵𝗲 𝗰𝗼𝗿𝗿𝗲𝗰𝘁 𝗚𝗦𝗧 𝗽𝗲𝗿𝗶𝗼𝗱?
𝗥𝗲𝘃𝗶𝗲𝘄 𝘆𝗼𝘂𝗿 𝗶𝗻𝘃𝗼𝗶𝗰𝗶𝗻𝗴 𝗮𝗻𝗱 𝗮𝗱𝘃𝗮𝗻𝗰𝗲-𝗽𝗮𝘆𝗺𝗲𝗻𝘁 𝗽𝗿𝗼𝗰𝗲𝗱𝘂𝗿𝗲𝘀 𝘁𝗼𝗱𝗮𝘆.
𝗖𝗔 𝗦𝗮𝗶𝗹𝗲𝘀𝗵 𝗕𝗵𝗮𝗻𝗱𝗮𝗿𝗶
#𝗚𝗦𝗧𝗜𝗻𝗱𝗶𝗮 #𝗚𝗦𝗧𝗖𝗼𝗺𝗽𝗹𝗶𝗮𝗻𝗰𝗲 #𝗧𝗶𝗺𝗲𝗢𝗳𝗦𝘂𝗽𝗽𝗹𝘆 #𝗚𝗦𝗧𝗨𝗽𝗱𝗮𝘁𝗲𝘀𝟮𝟬𝟮𝟲 #𝗚𝗦𝗧𝗥𝗲𝘁𝘂𝗿𝗻𝘀 #𝗠𝗦𝗠𝗘𝗜𝗻𝗱𝗶𝗮 #𝗖𝗵𝗲𝗻𝗻𝗮𝗶𝗕𝘂𝘀𝗶𝗻𝗲𝘀𝘀
 Call Now