
Blog Detail
𝗕𝗲𝘆𝗼𝗻𝗱 𝗦𝗮𝗹𝗲𝘀 𝗜𝗻𝘃𝗼𝗶𝗰𝗲𝘀: 𝗧𝗵𝗲 𝗚𝗦𝗧 𝗧𝗿𝗮𝗻𝘀𝗮𝗰𝘁𝗶𝗼𝗻𝘀
𝗘𝘃𝗲𝗿𝘆 𝗚𝗿𝗼𝘄𝗶𝗻𝗴 𝗕𝘂𝘀𝗶𝗻𝗲𝘀𝘀 𝗦𝗵𝗼𝘂𝗹𝗱 𝗥𝗲𝘃𝗶𝗲𝘄
ㅤ
Many business owners assume GST applies only when an invoice is raised and money is received.ㅤ
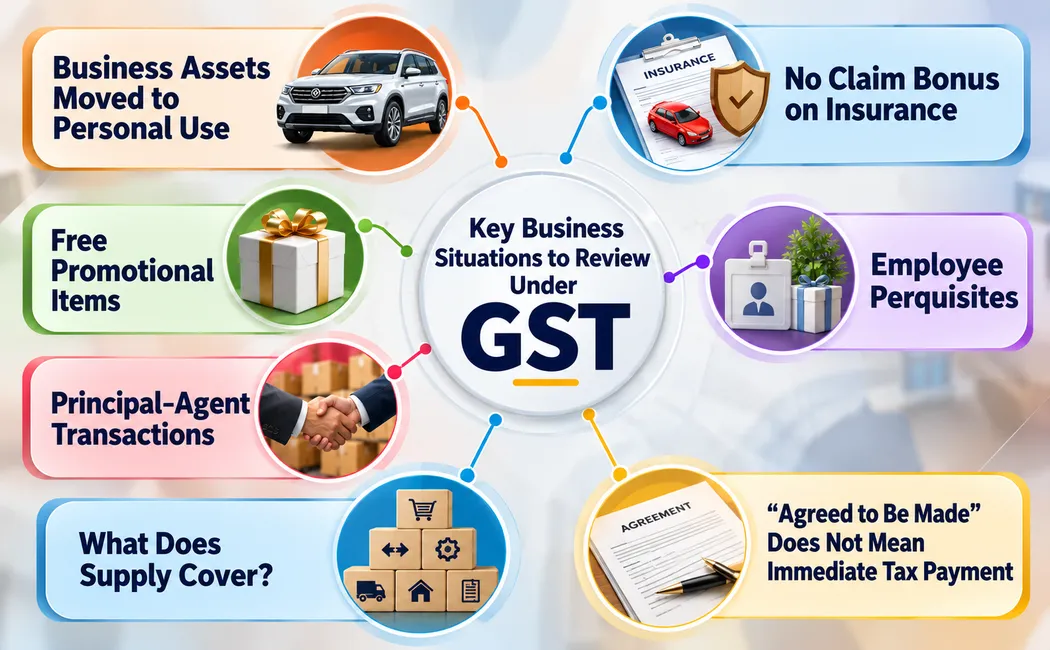
But as businesses grow, transactions involving assets, free promotions, agents and employee benefits can create GST implications even when they do not look like normal sales.
ㅤ
For businesses with turnover between ₹5 crore and ₹500 crore, these areas deserve regular review.
ㅤ
𝗕𝘂𝘀𝗶𝗻𝗲𝘀𝘀 𝗔𝘀𝘀𝗲𝘁𝘀 𝗧𝗮𝗸𝗲𝗻 𝗳𝗼𝗿 𝗣𝗲𝗿𝘀𝗼𝗻𝗮𝗹 𝗨𝘀𝗲
Suppose a Coimbatore automobile dealer takes a vehicle from stock permanently for personal use.
If Input Tax Credit (ITC) was availed, permanent transfer or disposal of such business assets can be treated as a supply even without consideration under Schedule I.ㅤ
𝗙𝗿𝗲𝗲 𝗣𝗿𝗼𝗺𝗼𝘁𝗶𝗼𝗻𝗮𝗹 𝗜𝘁𝗲𝗺𝘀
ㅤ
A business may distribute free samples or promotional products.ㅤNot every free supply automatically becomes taxable.ㅤ
However, businesses should check whether Schedule I applies and whether ITC reversal under Section 17(5)(h) is required for gifts or free samples.
ㅤ
𝗣𝗿𝗶𝗻𝗰𝗶𝗽𝗮𝗹–𝗔𝗴𝗲𝗻𝘁 𝗧𝗿𝗮𝗻𝘀𝗮𝗰𝘁𝗶𝗼𝗻𝘀
Businesses operating through agents should examine who issues the invoice and whether the agent has authority to pass or receive title to goods.
ㅤ
Certain principal–agent supplies can fall under Schedule I even without consideration.
𝗘𝗺𝗽𝗹𝗼𝘆𝗲𝗲 𝗕𝗲𝗻𝗲𝗳𝗶𝘁𝘀 𝗮𝗻𝗱 𝗡𝗼 𝗖𝗹𝗮𝗶𝗺 𝗕𝗼𝗻𝘂𝘀
Perquisites provided to employees as part of the employment contract are generally not subject to GST when they form part of the employment arrangement.ㅤ
Similarly, a No Claim Bonus is not consideration for a separate supply by the insured merely because no insurance claim was made.
ㅤ
𝗚𝗦𝗧 𝗶𝘀 𝘄𝗶𝗱𝗲𝗿 𝘁𝗵𝗮𝗻 𝗮 𝗻𝗼𝗿𝗺𝗮𝗹 𝘀𝗮𝗹𝗲. 𝗜𝘁 𝗰𝗮𝗻 𝗰𝗼𝘃𝗲𝗿 𝘀𝗮𝗹𝗲, 𝘁𝗿𝗮𝗻𝘀𝗳𝗲𝗿, 𝗯𝗮𝗿𝘁𝗲𝗿, 𝗲𝘅𝗰𝗵𝗮𝗻𝗴𝗲, 𝗹𝗶𝗰𝗲𝗻𝗰𝗲, 𝗿𝗲𝗻𝘁𝗮𝗹, 𝗹𝗲𝗮𝘀𝗲 𝗮𝗻𝗱 𝗱𝗶𝘀𝗽𝗼𝘀𝗮𝗹.
𝗕𝘂𝘀𝗶𝗻𝗲𝘀𝘀 𝗧𝗮𝗸𝗲𝗮𝘄𝗮𝘆:
Review free supplies, asset transfers, agent arrangements and employee benefits periodically.
ㅤ
𝗔 𝘁𝗿𝗮𝗻𝘀𝗮𝗰𝘁𝗶𝗼𝗻 𝘄𝗶𝘁𝗵𝗼𝘂𝘁 𝗽𝗮𝘆𝗺𝗲𝗻𝘁 𝘀𝗵𝗼𝘂𝗹𝗱 𝗻𝗲𝘃𝗲𝗿 𝗯𝗲 𝗮𝘀𝘀𝘂𝗺𝗲𝗱 𝘁𝗼 𝗵𝗮𝘃𝗲 𝗻𝗼 𝗚𝗦𝗧 𝗶𝗺𝗽𝗮𝗰𝘁 𝘄𝗶𝘁𝗵𝗼𝘂𝘁 𝗰𝗵𝗲𝗰𝗸𝗶𝗻𝗴 𝗶𝘁𝘀 𝗻𝗮𝘁𝘂𝗿𝗲 𝗳𝗶𝗿𝘀𝘁.ㅤ
CA Sailesh Bhandariㅤ
#GST #GSTIndia #BusinessOwners #MSMEIndia #TaxCompliance #Entrepreneurs #InputTaxCredit #CGST
 Call Now