
Blog Detail
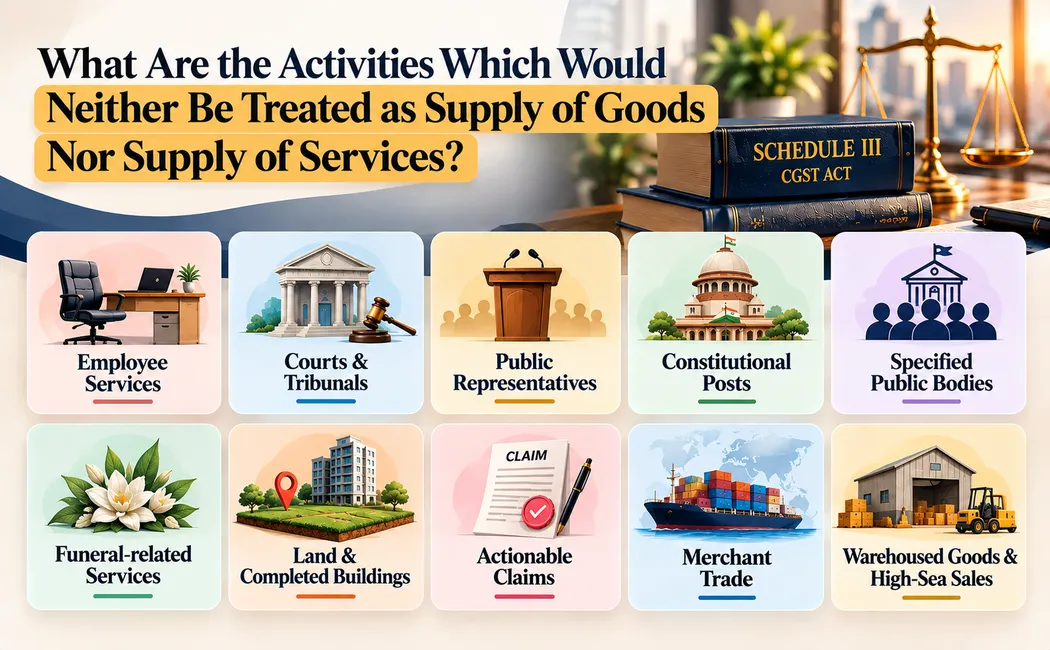
What Are the Activities Which Would? Neither Be Treated as Supply of Goods Nor Supply of Services?
Schedule III of the CGST Act identifies specified activities and transactions that are treated as neither a supply of goods nor a supply of services
Therefore, GST does not begin merely because a transaction or activity exists.
For businesses with turnover of ₹5 crore to ₹500 crore,
this distinction becomes important as operations expand across employees, property, imports, exports and international trade.
Correct classification at the outset can prevent unnecessary GST treatment and reporting issues.
| Situation No. | Activity | Schedule III |
| Situation i | Employee services |
Services by an employee to the employer in the course of or in relation to employment.
|
| Situation ii | Courts & Tribunals |
Services by any court or tribunal established under any law.
|
| Situation iii | Public representatives |
Functions performed by MPs, MLAs and members of Panchayats, Municipalities and other local authorities.
|
| Situation iv | Constitutional posts |
Duties performed by persons holding posts under the Constitution.
|
| Situation v | Specified public bodies |
Duties performed by specified Chairpersons, Members or Directors of government/local-authority bodies where they are not treated as employees.
|
| Situation vi | Funeral-related services |
Funeral, burial, crematorium or mortuary services, including transportation of the deceased.
|
| Situation vii | Land & completed buildings |
Sale of land and, subject to prescribed conditions, sale of completed buildings.
|
| Situation viii | Actionable claims |
Actionable claims, other than specified actionable claims.
|
| Situation ix | Merchant trade |
Goods supplied from one non-taxable territory to another without entering India.
|
| Situation x |
Warehoused goods & high-sea sales |
Specified supplies of warehoused goods and sale by endorsement of title documents before clearance for home consumption.
|
Business Takeaway:
Before determining the GST rate,
businesses should first ask whether the transaction qualifies as a supply at all.
A periodic Schedule III review can help finance teams classify transactions correctly and avoid unnecessary GST complications.
CA Sailesh Bhandari
#GST #GSTIndia #BusinessOwners #MSMEIndia #TaxCompliance #Entrepreneurs #CGST
 Call Now